FOR FILIPINO PROFESSIONALS IN SINGAPORE EARNING STABLE INCOME
How To Potentially Retire Comfortably Here or Back Home
Without Touching Your Capital and Without Reducing Your “Padala”
(The Money You Send Back Home)
Without Touching Your Capital and Without Reducing Your “Padala” (The Money You Send Back Home)
Paid in Singapore dollars, not pesos
Why Work With Me
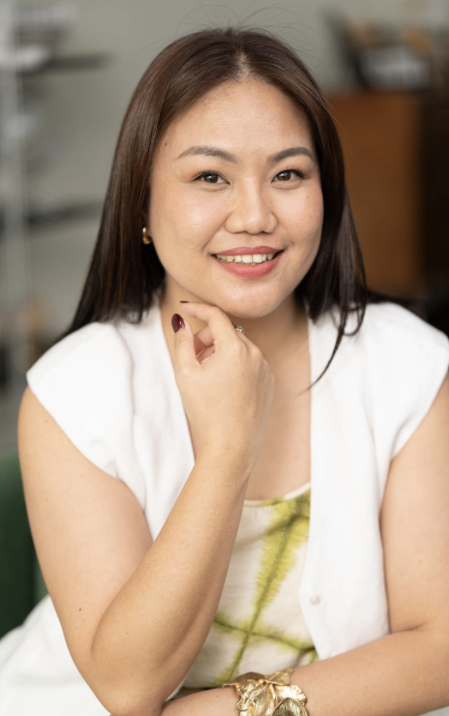
Nowella Joy Labasbas · Filipino. Singapore PR. 19 Years In Singapore.
01
A local Financial Adviser Representative (FA Rep) can only see half your money. I can see all of it.
I'm Filipino. I'm a PR. Nineteen years in Singapore. I send money home every month, same as you.
Sit down with a Singaporean FA Rep and he'll provide a comprehensive review of the Singapore portion of your financial plan. CPF, your policies, your salary. All captured neatly.
Everything you own in the Philippines gets left out.
He asks about your CPF. He has never once asked about your SSS (the Philippine Social Security System) and PAG-IBIG (the Philippine core provident fund).
He maps your Singapore policies. He knows your salary to the dollar. He’s not aware of the assets you own in your home country. He considers the money you send home as an expense. He suggests you trim it, leading you to lose confidence in his financial planning advice.
That spending isn't discretionary. Your aging parents are a 3 to 4 hour flight away, with no pension and no medical plan behind them. You’re their only financial safety net.
I am never going to ask you to send home less money. So we plan around it.
I walk you through both sides: what's growing in Singapore, what's tied up in the Philippines. You see the full picture, not just half of it. Clarity first. Everything else follows.
Filipinos are some of the hardest working people I know. But too often, all that work doesn't translate into real wealth. Too many “kababayan” (fellow Filipinos) come home older and lesser than what they started with. I refuse to let that be your story too. Money should give you choices, not leave you starting over.
You want to work with someone who doesn't just see your numbers. Someone who sees you: the son, the daughter, the husband, the wife, the one supporting the family back home.
02
I made the mistake of investing in properties in Manila without first establishing a long-term savings plan.
I started buying properties in Manila. Twelve years later, they are worth about the same as what I paid. There is no appreciation in the prices of the properties and I only receive rental income occasionally which is in peso, a currency that has generally been weaker than the Singapore dollar over the long term.
This is not the retirement income I had envisioned. Then I started building a portfolio in Singapore dollar which changed my initial plan.
03
Retire in the wrong currency and you get poorer.
The Singapore dollar has generally been stronger than the Philippine peso over the long term.
Retire on an income in peso while living in Singapore, and you get poorer every year.
Retire in the Philippines on an income in SGD, and it buys you more every year.
04
You don't need big capital. I didn't have any.
I placed a fixed portion of my income in investment. Same as what you would do.
The question was never “do I have enough to start.” It's “what percentage of what I already earn goes somewhere it compounds, instead of somewhere it disappears.”
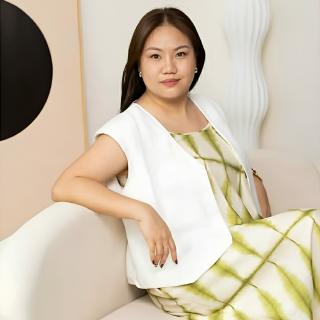
As a Singapore PR and a Filipino, I get asked a lot of questions: how to save better, how to start investing, how to grow what little is left each month or how to get out of debt. But underneath all of it, it's really one question: how do I build a fulfilling life, for myself and for the people I love?
And I've come to realise a fulfilling life starts with money. Get that right, and your options open up. Money isn't the whole story, but it's often the thing standing between wanting to help, nurturing others, making a difference, and actually being able to.
Which is why I'm inviting you into a conversation, not a sales pitch. No products to buy.
Because buying in a hurry, without a game plan, can sometimes hurt more than it helps. I know this firsthand. It's exactly what happened when I bought my Manila property.
If you want a finance professional who understands your exact situation, someone who can walk with you and hand you an idea or two, let's talk.
Here's How I Take You From Working Hard To Retiring Well
01
Consolidation
Everything you have in both countries – the "padala" (remittances) you send home, the loans, the insurance, the "ipon" (savings), CPF, SSS and PAG-IBIG. You see where you stand today and where you want to be, for yourself and the family counting on you.
02
Clarity
Once all the pieces are put together, you will get to see what you are missing.
03
Choices
Now you can see the options more clearly. Practical ways to close the gaps, whether your goal is owning a home in Singapore, providing security for your family in the Philippines, or achieving both.
04
Control
Every Juan, every Filipino, can retire. It just takes courage to plan for it. With the right choices in place, your finances stop controlling you, and you take control of your financial destiny.
Check Out My Case Studies
After 10 Years of DIY Investing, He Wanted a Review of His Insurance and Investment Portfolio
IT Service Delivery Manager, 44
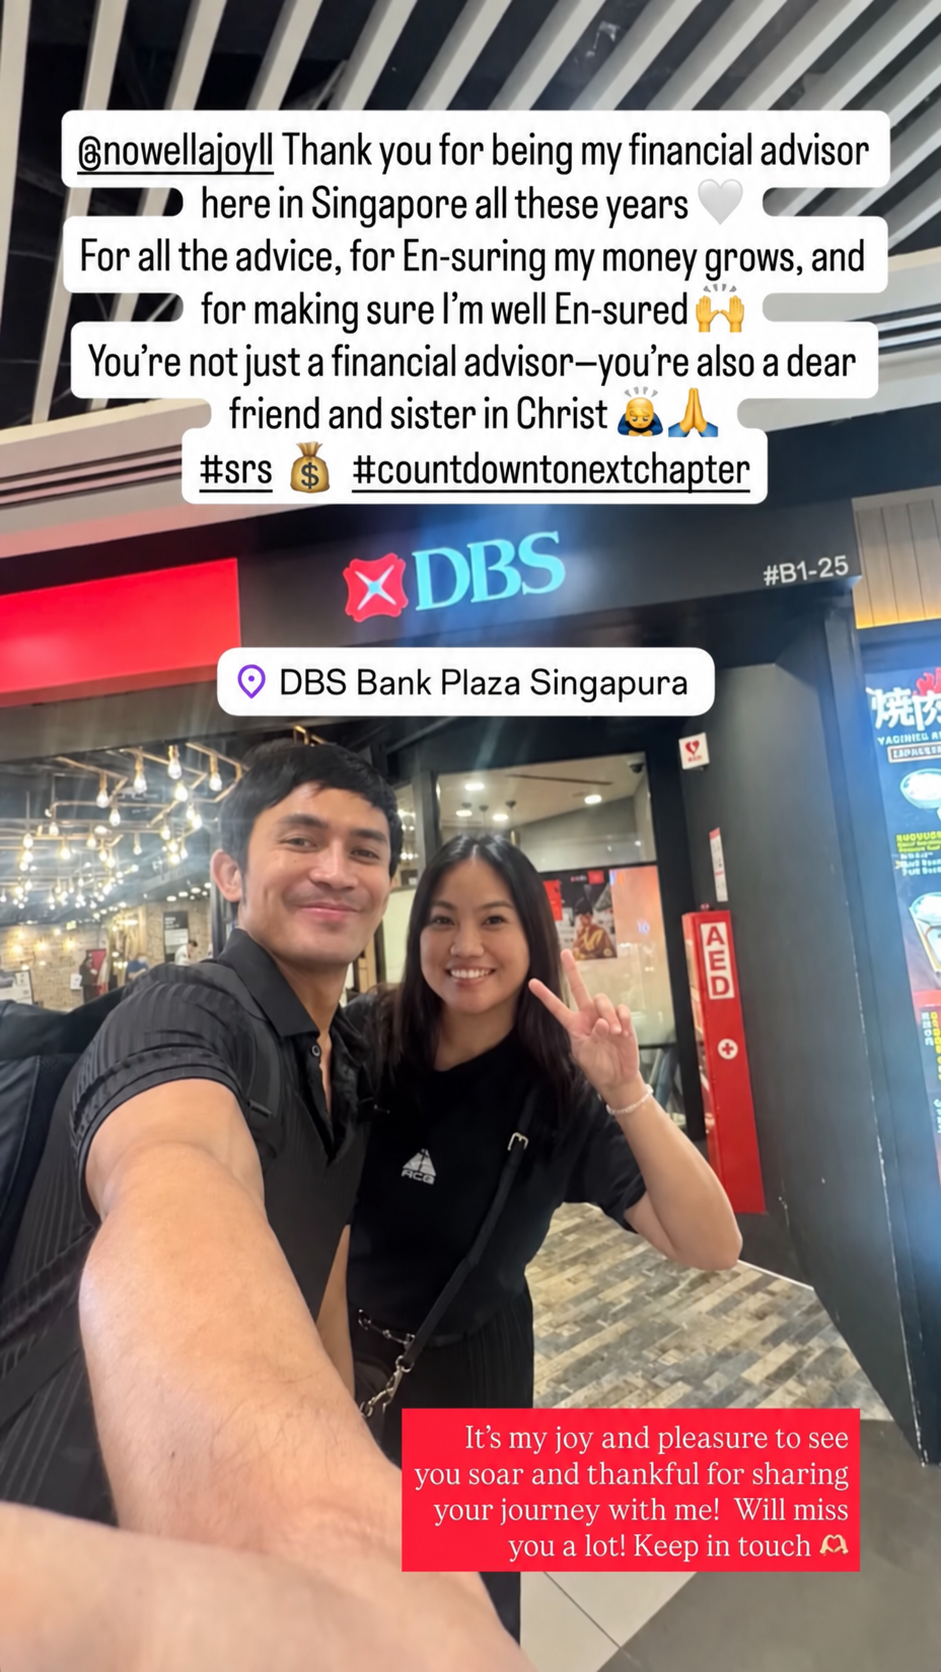
My insurance client for more than 10 years
Invested on his own for 10+ years
Growth stayed modest
Nowella mapped his portfolio against real career goals and time horizon
Found portfolio holdings with significant overlap and redundancy
Rebuilt his portfolio with risks explained upfront
Within 2 months, new portfolio outperformed his 10+ years of DIY approach
Kept up regular reviews to keep him on track
Relocated overseas in Q2 2026 but kept Singapore portfolio running as planned
Proved the strategy holds even when life changes
Individual results vary. Past performance is not indicative of future returns.
From a SGD 4,000 Loss To Almost Half A Million Pesos In Investment Growth
IT Application Support, 43
Invested $20,000 on his own → dropped to $16,000, a $4,000 loss
Ready to walk away from investing altogether
Met Nowella, worked with what he had left instead of adding fresh capital
Tested whether the investment fundamentals would actually work for him
Consistent check-ins
Client attended exclusive investment events to build his knowledge
Became comfortable taking on more risk, not because the market got safer, but because he understands what he's invested in and why
Steady monitoring, ad-hoc fund switches when good opportunities came up
A collaborative effort, client had a real say in every move
Consistent investment top-ups
No panic selling during dips, no chasing hype during spikes
Focused on “am I on track for retirement,” not “did I make money today”
No longer reacting to fear, just staying disciplined together
Individual results vary. Past performance is not indicative of future returns.
From An Inheritance She Couldn't Touch to Monthly Income She Can Count On
Widow & Homemaker, 52
Husband passed away, inherited his 7-figure SGD estate, including insurance payouts
Previous FA Rep locked ~80% of it into whole life insurance and long-term investment plans
Didn't account for the fact that she had no income of her own, 2 children to support
Worried about daily expenses and her children's needs
Forced to find a job just to keep the household afloat
She reached out to Nowella when things started feeling overwhelming
After understanding what's going on, Nowella mapped out expense projections from 2024 until 2030 (school fees, monthly household needs, insurance premiums, etc)
Based on her income needs, Nowella reallocated part of her portfolio into income-generating assets, with a multi-year strategy to turn sleeping assets into a healthier, steadier cashflow, while keeping her existing protection coverage in place
Gave her room to breathe, instead of pressure to keep working
She can now choose when to return to work, instead of being forced to by necessity
Individual results vary. Income from endowments, investment-linked plans and other types of investments are not guaranteed and depend on prevailing rates and fund performance.
From Saving Blindly to Reaching 50% of Her Retirement Goal
Data Analyst, 52
Always the one sending money home, helping family whenever needed
Recurring worry: when she's old and can't work, who's going to take care of her?
Decided not to expect anything back from the people she supported, chose to build her own safety net instead
Already working hard and saving, but no real plan, just putting money aside without knowing if it was enough or where it should go
Knew she needed a proper retirement plan, didn't know how to start one
Nowella started with one question: what does your retirement actually look like?
She wanted independence, knowing she couldn't depend on anyone else to take care of her
Nowella mapped out her ideal lifestyle, built the plan in stages instead of one rushed sit-down
Currently on track, hit 50% of her retirement goal
More motivated than ever to keep closing the gap
Individual results vary. Income from endowments, investment-linked plans and other types of investments are not guaranteed and depend on prevailing rates and fund performance.
Here's what we'll cover
Every asset from both countries in one page and in one currency.
The monthly retirement income you want and the capital you need to receive payouts for life.
I am an authorised Financial Adviser Representative from Beacon Advisers, an authorised group of Financial Adviser Representatives from Professional Investment Advisory Services Pte Ltd. PIAS Representative Name: Nowella Joy Labasbas and MAS RNF No.: LNJ200099339
The views and opinions expressed here are solely that of the author and do not reflect the opinion of Professional Investment Advisory Services Pte Ltd. The information provided here is for general and educational purposes only, does not constitute the provision of financial advisory services and does not have regard to the investment objectives, financial situation and needs of any specific person.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
©2026 Nowella Labasbas. All rights reserved.